 Bank accounts
Bank Accounts in Germany
N26, DKB, Commerzbank and Revolut compared — free plans, ATM rules, IBAN types and what expats actually need.
Read the Germany guide →Independent, research-based guides for expats living in Europe: which bank accounts to open in Germany, France and Spain, how to transfer money abroad without losing a fortune, and which brokers Europeans can trust.
Popular free tools
From our own sites, made by the same team. No ads, no sign-up, free forever.
Every guide compares the most popular options among expats, explains fees in plain English, and flags the fine print — so you can verify everything on the provider's site before you commit.
Bank accountsN26, DKB, Commerzbank and Revolut compared — free plans, ATM rules, IBAN types and what expats actually need.
Read the Germany guide → Bank accounts
BoursoBank, Fortuneo, BNP Paribas and Revolut — free online banks vs. branch banking, and how expats get a French IBAN.
Read the France guide → Bank accounts
BBVA, Openbank, N26 and Revolut — which Spanish accounts are genuinely free, and what the NIE means for banking.
Read the Spain guide → Bank accounts
bunq, ING, ABN AMRO and Rabobank compared — BSN rules, Dutch IBAN and iDEAL, monthly fees and what newcomers need.
Read the Netherlands guide → Bank accounts
Intesa Sanpaolo, UniCredit, Fineco and the app banks — codice fiscale rules, Italian IBAN, canone and imposta di bollo fees.
Read the Italy guide → Bank accounts
ActivoBank, Millennium BCP, CGD and Novo Banco compared — NIF rules, MB WAY, Portuguese IBAN and real fees.
Read the Portugal guide → Bank accounts
AIB, Bank of Ireland, PTSB and An Post compared — plus the free N26/Revolut/bunq setup, card stamp duty and PPS rules.
Read the Ireland guide → Bank accounts
Belfius Beats Pulse (€0), Hello Bank! (€0), ING Do More Pack, KBC Brussels Plus, Wise & Revolut — the €0 setup vs €60+/year banks.
Read the Belgium guide → Bank accounts
N26 (€0), DKB (€0), bank99 smartkonto99 (€1.99), BAWAG PSK (€1.99), Erste Bank (€3.89) — plus the ING Austria trap and AT-IBAN rules.
Read the Austria guide → Bank accounts
Nordea, Swedbank, SEB and Handelsbanken vs N26 (€0) & Revolut (€0) — personnummer, BankID, Swish and real fees.
Read the Sweden guide → Bank accounts
Piraeus, Eurobank, Alpha Bank and NBG — the AFM tax-number rule, real fees and the €0 pre-arrival setup.
Read the Greece guide → Bank accounts
Danske Bank, Lunar and N26 — the CPR + MitID order, real fees and the 0-kr setup.
Read the Denmark guide → Bank accounts
OP, S-Pankki, Nordea and Danske compared — henkilötunnus rules, bank identifiers (e-ID), real fees and the €0 pre-arrival setup.
Read the Finland guide → Bank accounts
Zagrebačka banka, PBZ, Erste, OTP and Revolut compared — the OIB rule, non-resident accounts, HR-IBAN and the €0 pre-arrival setup.
Read the Croatia guide → Money transfers
Wise, Remitly, XE and Revolut compared on fees, exchange-rate markups and speed — for sending money home from Europe.
Read the transfer guide → Investing
Trade Republic, DEGIRO, Interactive Brokers and XTB — flat fees vs. commission-free, and which suits beginners.
Read the broker guide →Money advice should earn trust, not just clicks. Here's how we work.
Every comparison starts from providers' published price lists and 2026 third-party reviews. We re-check facts instead of copying marketing copy.
We compare options that are popular among expats — we never claim a single "#1 best" product. Suitability depends on your situation.
Some links may earn us a commission at no cost to you — see our affiliate disclosure. It never changes what we recommend.
A share of this site's earnings (5-10%) is pledged to help poor people. Read more on our about page.
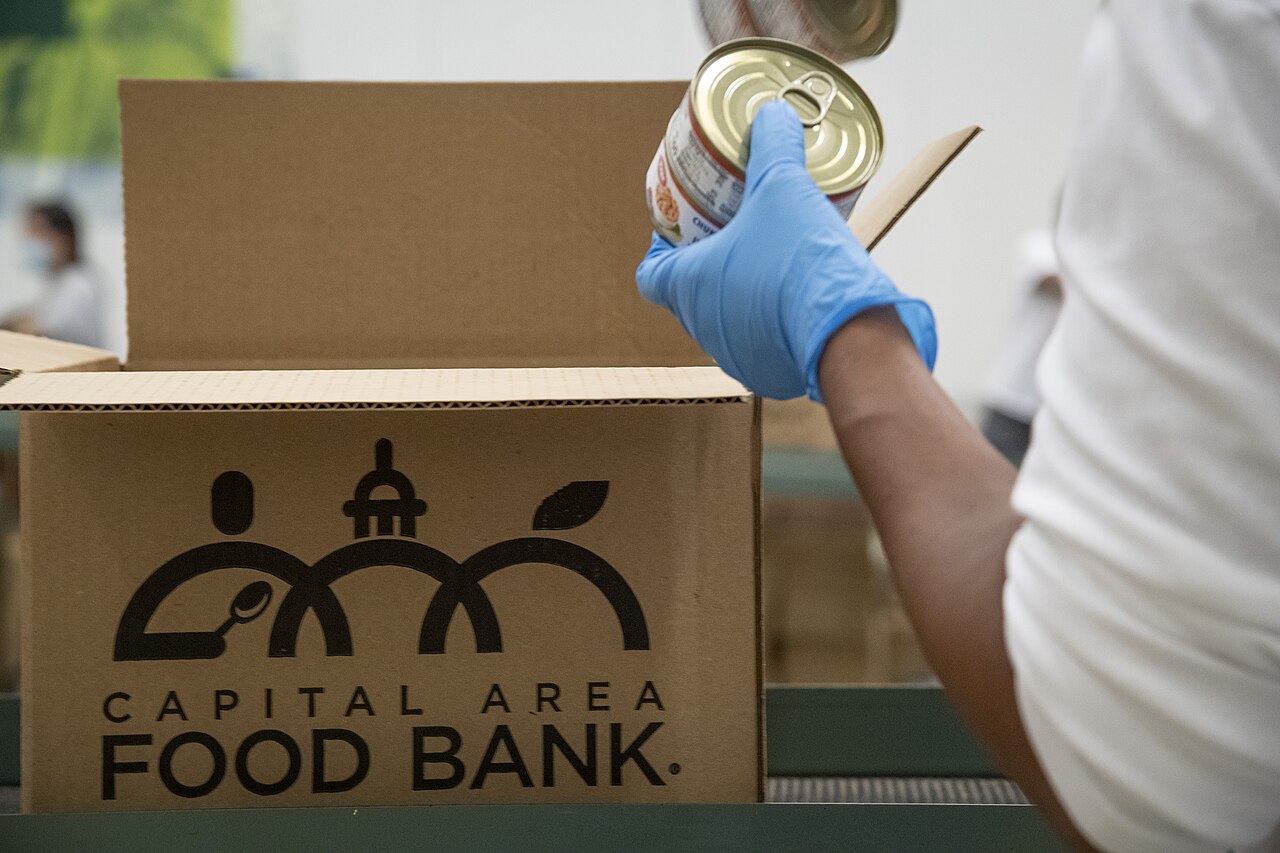
Photos: New York Public Library research room by Diliff / Wikimedia Commons, CC BY 2.5; Lady Justice statue by James Cridland / Wikimedia Commons, CC BY 2.0; euro coins and banknotes by Avij / Wikimedia Commons, public domain; food bank volunteer by USDA / Wikimedia Commons, public domain.
Short answers to the questions every new arrival asks.
Yes — in most EU countries you can open an account with a passport and proof of address. Germany's N26 even lets you open an account without city registration (Anmeldung). France's BoursoBank accepts EU IBANs at signup, so it works for newly arrived expats. Always check the provider's current eligibility rules before applying.
Thanks to SEPA IBAN non-discrimination rules, a German IBAN should be accepted for direct debits anywhere in the eurozone. In practice, some landlords, employers and insurers still insist on a local IBAN — so in France a real French (FR) IBAN is often worth having.
For most corridors, specialists like Wise beat traditional banks because they use the real mid-market exchange rate and charge a transparent fee. Remitly and XE can be cheaper for cash-pickup corridors or large amounts. Compare the amount that actually arrives — not just the advertised fee. See our money transfer guide.
EU banks protect deposits up to €100,000 per depositor under the statutory deposit guarantee scheme. Brokers segregate client securities, and cash is covered by deposit guarantees or investor compensation schemes (up to €20,000 for EU investment firms). Protections differ by legal entity, so check which entity holds your account.
No. Our guides are educational comparisons, not personalised financial advice. Everyone's tax residency, income and risk tolerance differ — for regulated advice, consult a licensed adviser in your country. Fees and features change often; always verify on the provider's official site before opening anything.